020 8668 6080

Mortgages

First-Time Buyer Mortgage Advice

Buying your first home, step by step: deposits, what you could borrow, the application and everything up to getting the keys.

Buying your first home is exciting, but the mortgage side can feel like a maze. We explain how much you could borrow, which lenders suit your income and deposit, and what each step involves, so you can make offers with confidence rather than guesswork.
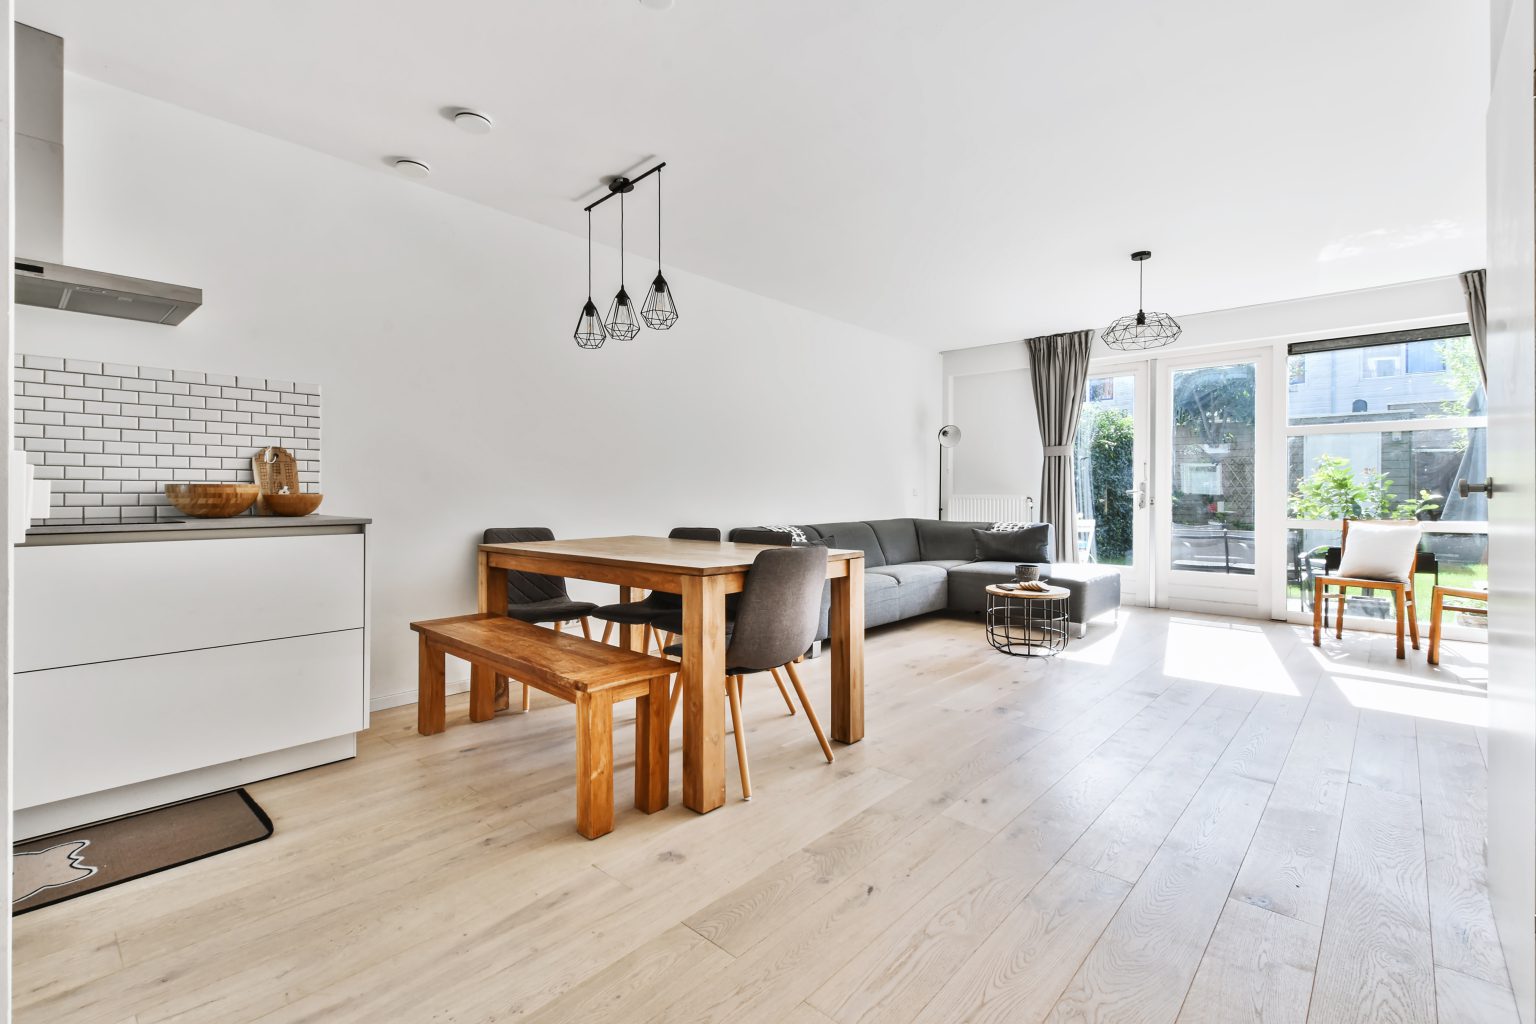
An open-plan kitchen and living room filled with daylight
Mortgage advice tailored to your property plans, with 90+ lenders compared.

Most lenders want a deposit of at least 5% to 10% of the purchase price, and a bigger deposit usually unlocks lower rates. Your deposit can come from savings, a Lifetime ISA, or a gift from family, which most lenders accept with a signed gifted deposit letter. If your income alone does not stretch far enough, some lenders offer joint borrower sole proprietor mortgages, where a parent's income supports the application without them going on the deeds.

Before you start viewing, we will get you an Agreement in Principle, which shows estate agents you are a serious buyer. We also check your credit file with you first, because small things like a missed phone bill or not being on the electoral roll can change which lenders will say yes.

Beyond the deposit, budget for the survey, your solicitor's fees, and Stamp Duty Land Tax if it applies. First-time buyers can get relief on Stamp Duty depending on the purchase price; we will point you to the current thresholds when we work out your figures.

New-build flats, shared ownership and leasehold properties each come with their own lender rules. We check these before you pay a reservation fee, so there are no surprises once your offer is accepted.
90+ UK LendersHigh-street and specialist lenders compared
£0 Renewal FeesNo fee when we arrange your next deal
Bespoke AdviceAdvice centred on your circumstances
Frequently asked questions

First-Time Buyers questions

A family unpacking cardboard boxes on the floor of their new home
  • Some lenders accept a 5% deposit, but more choice and lower rates usually open up at 10% and above. We will show you what is available at your deposit level and whether saving a little more would make a meaningful difference.

  • Yes. Most lenders accept a gifted deposit from a family member, supported by a gifted deposit letter confirming it is a gift, not a loan. Some lenders also offer mortgages where a parent's income helps you borrow more without them owning part of the home.

  • Most lenders lend around 4 to 4.5 times your income, and some lend more for certain professions or higher earners. Your outgoings, credit history and deposit all affect the figure, so we check it against real lender criteria rather than a single multiple.

  • Yes, provided you meet the Lifetime ISA rules for a first home, including the purchase price limit and using a conveyancer to request the funds. Let us know early, because the withdrawal has to be requested through your solicitor before completion.

  • We may charge a broker fee for mortgage advice depending on your circumstances. A typical fixed fee is £479, payable on offer, and the fee is always confirmed before you proceed. Your first conversation with us is without obligation.

How it works

Your first-time buyer journey

From working out your budget to collecting the keys, we stay with you at every stage.

  1. 01

    Initial consultation

    Speak to PMS for an initial consultation to assess your affordability and an indication of the type of borrowing available to you within the mortgage market.

    Affordability assessed across 90+ lenders
  2. 02

    Full consultation

    If you're happy to go ahead, PMS will book a full consultation either by Zoom or face to face with your adviser. You will be given a mortgage Agreement in Principle confirming your maximum borrowing, putting you in a strong position when offering on a property.

    Agreement in Principle secured
  3. 03

    We handle the detail

    Once you have found a property we take care of everything else: the mortgage application, surveys, solicitors, searches and dealing with any estate agents or developers on your behalf.

    Application, surveys and legal work managed
  4. 04

    Support to completion

    Your dedicated case manager and your adviser will be on hand to guide you through the whole process.

    Supported right through to completion

Ready to take the first step?

Your initial consultation is without obligation. Speak with an adviser in Croydon or over Zoom.

020 8668 6080

Let's take the next step

Book a no-obligation consultation with one of our expert advisers today.

Call us on 020 8668 6080