What we arrange
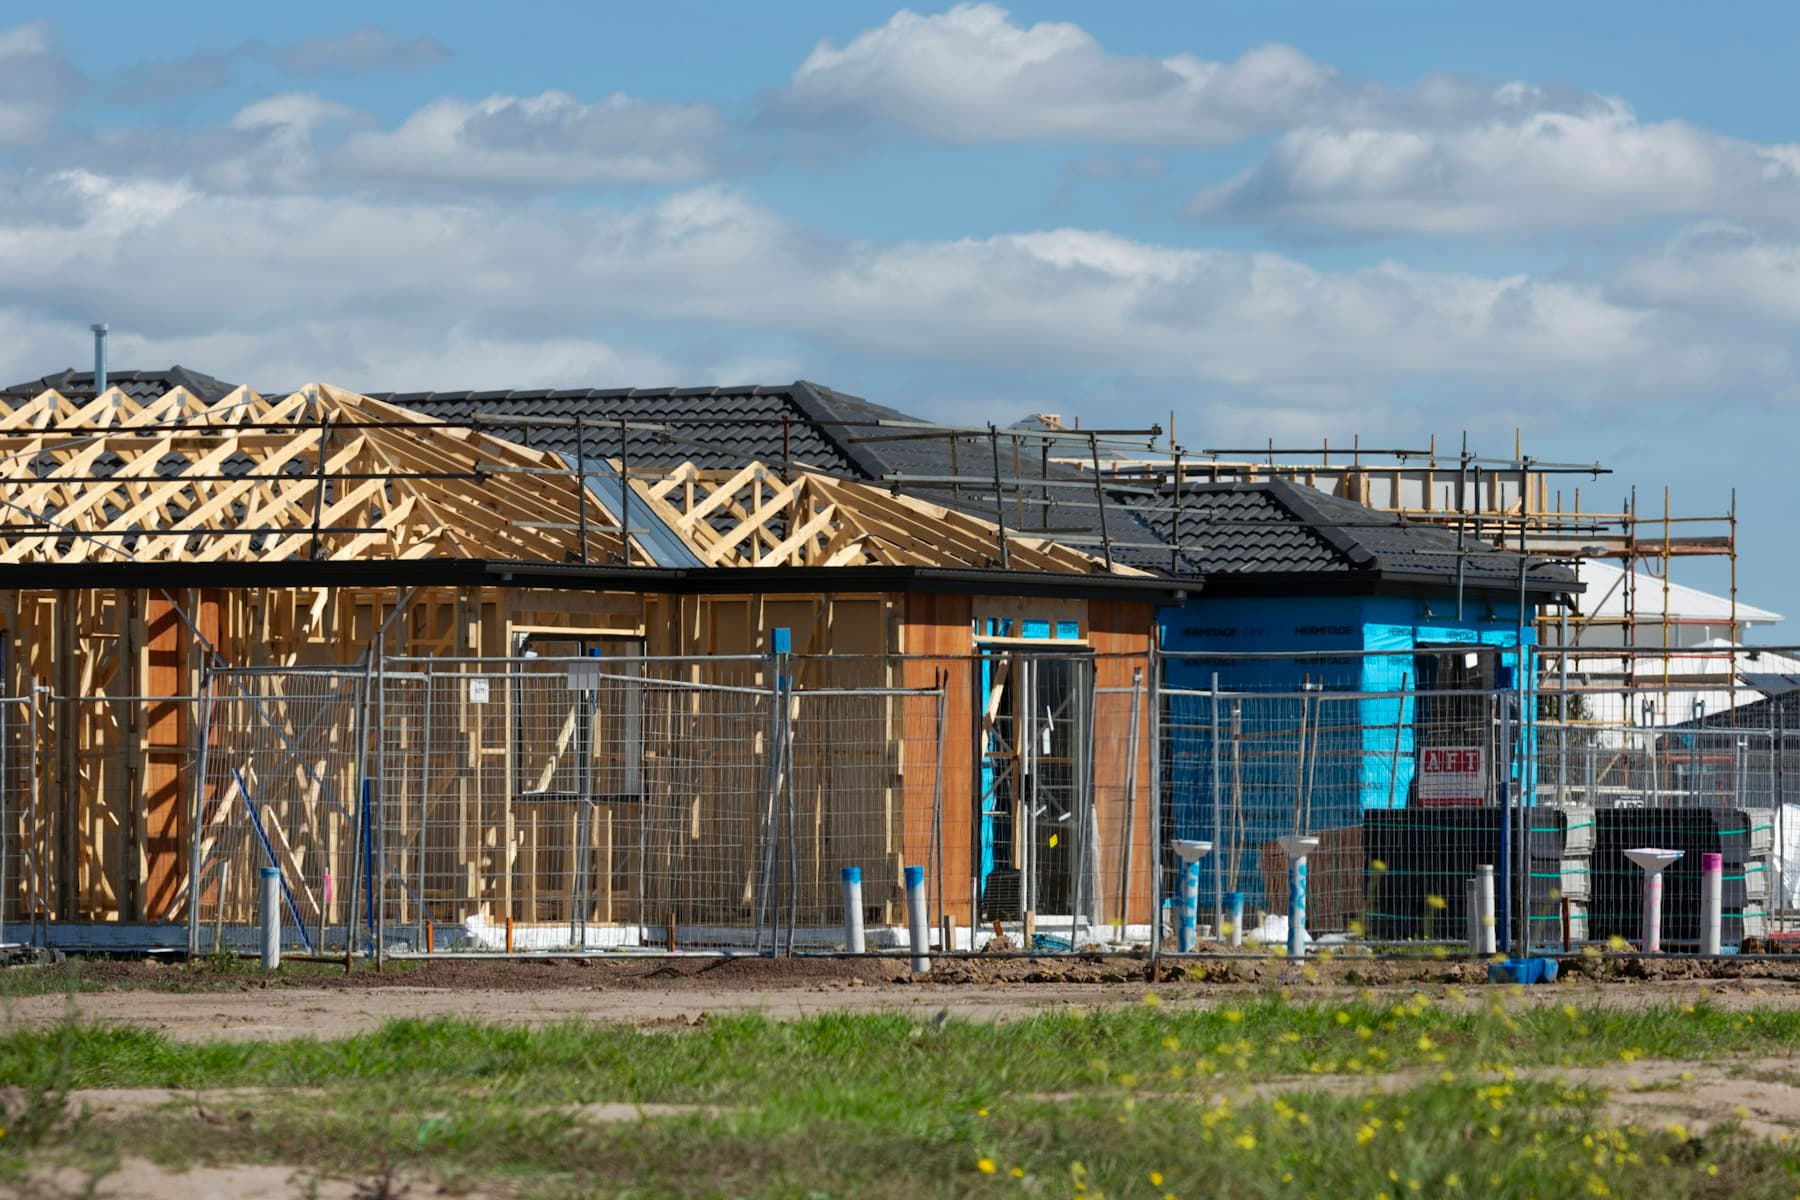
Ground-up development, from a single new home to multi-unit residential schemes
Conversions, including commercial to residential and permitted development schemes
Heavy refurbishment where works go beyond what a standard bridging loan will fund
Site acquisition, including bridging to secure a site while planning is finalised
Development exit finance to repay your development loan while units sell or let
How lenders assess a scheme
Development lenders look at the scheme as a whole. They will consider the gross development value (GDV) of the finished units, the total costs including land, build, fees and contingency, your experience and your professional team, the planning position and how the loan will be repaid at the end. We help you present each of these clearly, which makes a real difference to the terms you are offered.
How the money is released
Lenders usually advance part of the funding at the start to help with the site purchase, then release build costs in stages. Before each drawdown, a monitoring surveyor checks the work done. Interest is often rolled up or retained rather than paid monthly, so it is important to build it into your appraisal from day one.
What to prepare
a development appraisal with costs, GDV and expected profit
planning permission and drawings
a build programme and contractor details or quotes
details of your previous projects and your professional team
your exit strategy: sale, refinance onto buy-to-let, or a mix of both
Experienced and first-time developers
Experienced developers have the widest choice of lenders and terms. First-time developers can still find funding, particularly with a strong professional team and a realistic appraisal, but options are more limited. We will tell you honestly what is achievable for your scheme.
Frequently asked questions
Is development finance regulated?
Development finance for schemes you will sell or let is not regulated by the Financial Conduct Authority. If you are building a home to live in yourself, see our self-build mortgages page.
How much can I borrow?
It depends on the lender, your experience and the scheme. Lenders measure the loan against the total costs and the GDV. We look at your appraisal and tell you what level of funding is realistic.
Can you help with the exit?
Yes. Many developers keep some units to let. We can arrange development exit finance or refinance completed units onto buy-to-let mortgages, and we plan this at the start of the project.
Is there a fee?
A fee may be chargeable on large commercial loans and more complex scenarios, based on the time required. Any fee will be explained and agreed with you before we proceed.
Development finance for schemes you will sell or let is not regulated by the Financial Conduct Authority.
Your property may be repossessed if you do not keep up repayments on any loan secured against it.
All lending is subject to the lender's criteria, valuation and full underwriting.
A fee may be chargeable on large commercial loans and more complex scenarios, based on the time required. Any fee will be explained and agreed with you before we proceed.