Finance released as your home takes shape
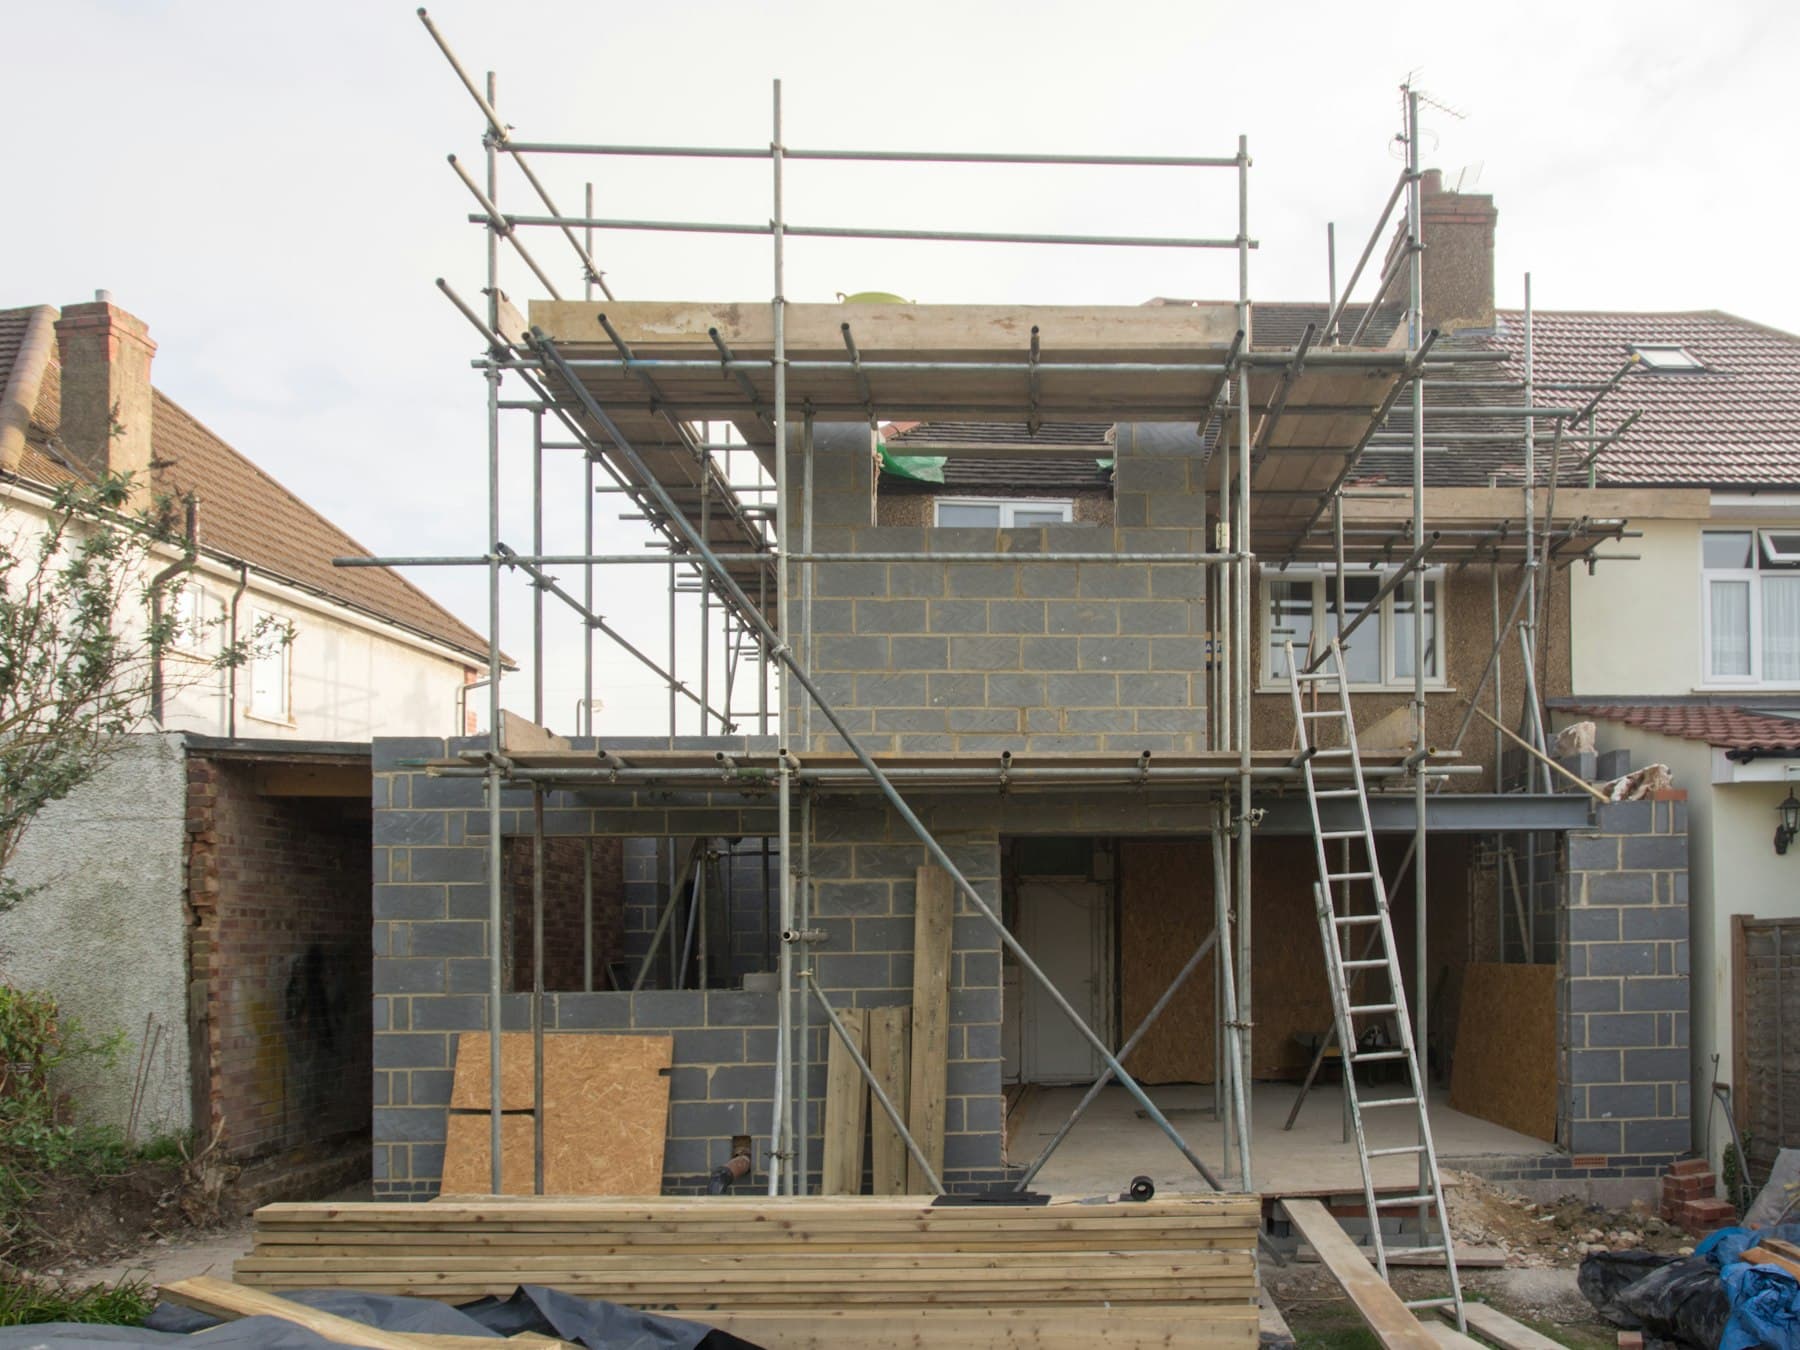
A standard mortgage lends against a finished home. A self-build mortgage releases money in stages as the build progresses, so you have funds when you need them. Each release usually follows a check by the lender's valuer that the stage is complete.
Typical stages are:
buying the plot, where the lender will fund it
foundations
wind and watertight (walls and roof)
first fix (plumbing, electrics and internal walls)
second fix and finishing
completion and final sign-off
Arrears or advance stage payments
Arrears stage payments are released after each stage is finished, so you need enough cash to fund each stage before you are paid back. Advance stage payments are released at the start of each stage, which makes cash flow easier but is offered by fewer lenders. We look at your savings, costs and timetable to work out which suits your build.
What lenders will want to see
full planning permission and building regulations approval
architect's drawings and a detailed build costing
a realistic build schedule and who will carry out the work
a structural warranty or architect's certificate for the finished home
evidence of your deposit and a contingency for unexpected costs
Who we help
people buying a plot and building their own home
custom build and kit or timber-frame homes
knocking down and rebuilding an existing property
major renovations and conversions you will live in
When the build is finished
Once your home is complete and signed off, the self-build mortgage can usually move onto, or be refinanced to, a standard residential mortgage. We plan for this from the start so there are no surprises at the end of the build.
Frequently asked questions
Can a self-build mortgage pay for the land?
Some lenders will lend towards the plot purchase, usually once planning permission is in place. Others expect you to own the land outright. We will tell you which approach fits your plans.
Do I need planning permission before applying?
Most lenders want full planning permission before they release funds for the build. You can still speak to us earlier, so you know what is possible and can plan your budget.
How much deposit will I need?
It depends on the lender, the value of the plot and your build costs. Lenders will also expect a contingency for overruns. We will work through the numbers with you before you commit.
Is a self-build mortgage regulated?
Yes. A self-build mortgage on a home you will live in is regulated by the Financial Conduct Authority, in the same way as a standard residential mortgage.
I am building to sell or let. Is this the right page?
If you are building to sell or rent out, you will usually need development finance instead. See our development finance page or speak to us.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Self-build mortgages are subject to the lender's criteria, a satisfactory valuation at each stage and full underwriting.